For many people, building credit is a routine step toward financial stability. But for new Americans and others starting over, it can be a significant barrier. Without a credit history, renting an apartment, buying a car, or qualifying for a loan is out of reach.
That’s where an innovative program supported by the Baltimore Community Foundation is making a difference. BCF has made multiple impact investments with the national nonprofit loan fund International Rescue Committee’s Center for Economic Opportunity (IRC-CEO) in Baltimore, between 2020 and today. IRC-CEO in turn uses the money to provide credit-establishing or building loans primarily to refugees and to their neighbors who were born in the United States, who may also lack access to affordable financing.
For BCF, this work is part of a broader strategy. Through its Invest for More initiative, the foundation directs a portion of its assets toward investments that generate financial returns while also addressing local challenges. Instead of relying on grantmaking alone, BCF uses impact investing to expand access to capital and support long-term economic participation.
A Partnership Model Rooted in Trust
IRC-CEO’s model depends on collaboration. The organization partners with nonprofits that provide financial education, workforce training, or other services. Some of these partners are IRC offices, while others are independent nonprofits embedded in Baltimore communities.
“We look for organizations that already have the trust in a community,” said Joshua Geary, Communications Manager for IRC-CEO. “Then we offer them a safe and affordable menu of loan products for their clients.”
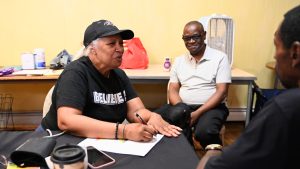
Clients typically reach IRC-CEO through partner organizations where they are already receiving financial counseling or other services. That combination of coaching and credit access helps borrowers use loans as a tool, not a risk. CEO calls this “lending as a service.”
Nonprofit partners bring relationships and insight into community needs. IRC-CEO provides the capital and lending infrastructure. The result is a system that lowers barriers for both borrowers and allows partner organizations to better serve their clients.
Small Loans, Measurable Impact
Credit-building loans through IRC-CEO are intentionally small, starting at $100 and increasing over time as borrowers successfully repay. They also feature a 0% interest rate. These loans help people establish a credit history through consistent, on-time payments.
Having no credit can limit access to opportunity as much as having poor credit. Many financial institutions require a track record before extending even basic services. Because credit scores are driven largely by payment history, even small loans can make a difference. Borrowers who complete their first loan often reach credit scores in the mid-600s within six months, creating a baseline they can build on.
From there, participants often move to practical next steps. Some open secured credit cards. Others refinance high-interest loans, purchase vehicles, or qualify for rental housing. Access to a reliable car, for example, can expand job options and increase earning potential.
A Tool for Many Starting Points
While IRC-CEO primarily serves refugees and immigrants, the need for credit-building tools is not limited to any one group. The program also serves U.S.-born individuals who need to rebuild credit or establish it for the first time. This includes people recovering from financial setbacks, individuals returning from incarceration, and participants in workforce programs. Across these groups, the challenge is similar: limited or damaged credit makes it harder to secure housing, employment, and financial stability.
By working through a range of nonprofit partners, IRC-CEO reaches people at different stages and in different circumstances. The loans are small, but the access they provide can affect many aspects of daily life.
BCF’s investment in IRC-CEO reflects a focus on expanding access to financial tools that are often out of reach. By supporting community development financial institutions and similar intermediaries, BCF can help extend responsible credit to people who are excluded from traditional systems while also recycling capital into future investments.
A Baltimore Family’s Story
For one family newly resettled in Baltimore, the program provided a starting point. After arriving in the United States as refugees, the Samba* family faced challenges finding employment, securing housing, and navigating the financial system. Through a local partner program, each family member participated in financial coaching and enrolled in credit-building loans.
Within a year, every member of the family saw improvements in their credit scores, moving from unscored or poor credit to fair or prime ranges. “The opportunity to build credit was very important for me and my family, and to feel connected to an organization,” said Joseph*, a member of the family. “We needed this support and connections.”
The impact extended beyond credit scores. With guidance from a financial coach, another family member refinanced a high-interest auto loan. This reduced monthly payments by half and saved approximately $15,000 over the life of the loan.
Today, members of the family are pursuing longer-term goals, including education, career advancement, and starting a business.
Local Investment, Continuing Impact
Since launching in Baltimore in 2020, IRC-CEO has made 219 loans totaling more than $870,000 in the region. Of those, 146 have been credit-building loans. While the organization operates in multiple states, Baltimore stands out as the only market where a community foundation has directly invested in this model—reflecting Baltimore Community Foundation’s focus on backing proven approaches rooted in local partnership.
IRC-CEO is continuing to expand its network of nonprofit partners in Baltimore and beyond, reaching more individuals through organizations providing financial education, workforce development, and reentry services. For BCF, this work demonstrates how aligning investment capital with community needs can extend access to credit and create durable pathways to financial stability—helping more residents build opportunity for the long term.
*Names have been changed to protect client privacy.